1. Who pays tax?
Every decision on tax rates and welfare involves a trade-off which requires wealthy people to support poor people. That’s part of a fair
society and a progressive tax system. At a high level, those who have look after those who have not.
There are infinite nuances. What about people who are able to work but choose not to? Should they be supported? That is why Centrelink has
rules that some welfare recipients need to demonstrate they have tried to find employment.
2. Investment properties
Let’s turn to assets, with most household wealth held in residential property, soon to top $10 trillion after the recent price surge
compared with about $3.2 trillion in superannuation.
Over 2.2 million Australians own investment property. That’s a lot of people enjoying the current housing boom (in addition to owners of
Principal Places of Residence). Over 20,000 own six or more properties and it’s party time funded by low interest rates.
3. Taxable incomes
For FY19, the average taxable income was $62,549. As this number is inflated by some very high earners, a more representative number is the median (as many people above the number as below) of $47,492.
4. Average superannuation balances by age
Most people do not have much in superannuation, with the median stated at less than $50,000 (and women $45,000), as shown above. This disguises balances by age. Obviously, older people have more super. Most have been in the system longer, have benefited from compounding and good market returns, earn more than younger people with more opportunities to contribute extra.
5. SMSFs
Turning to another ATO report, the SMSF
statistics for June 2021,
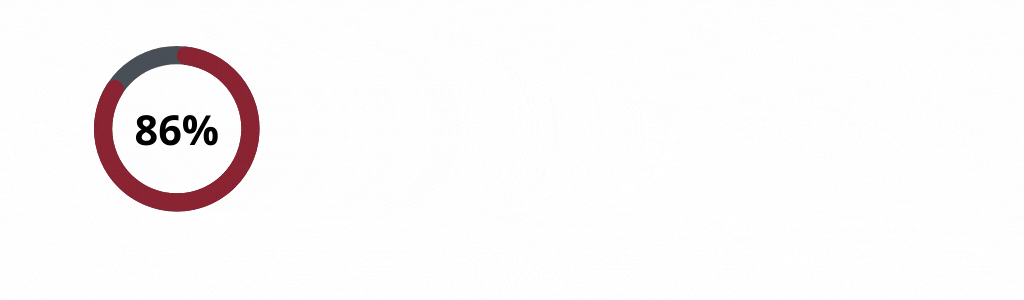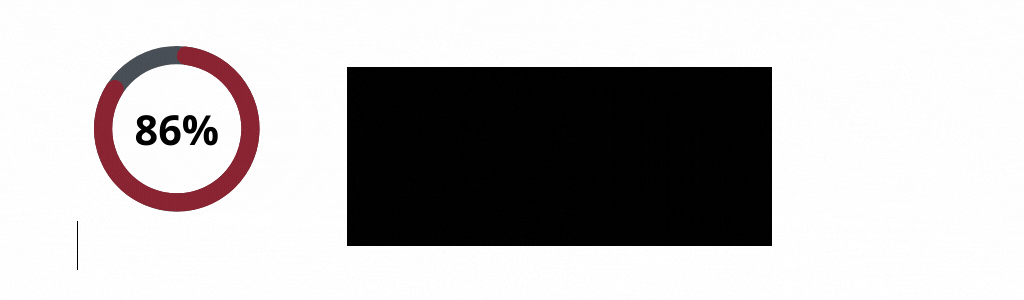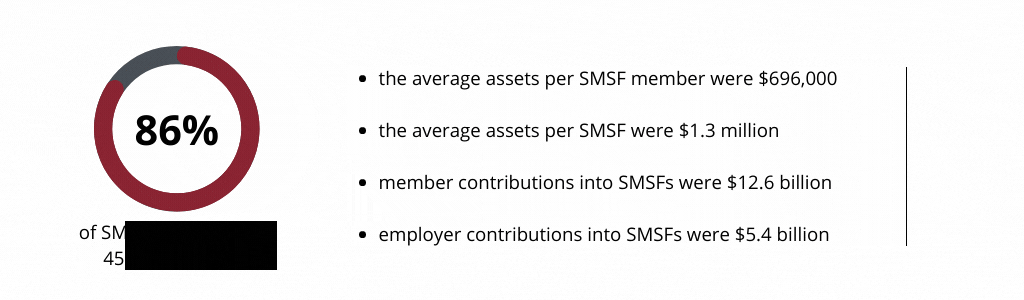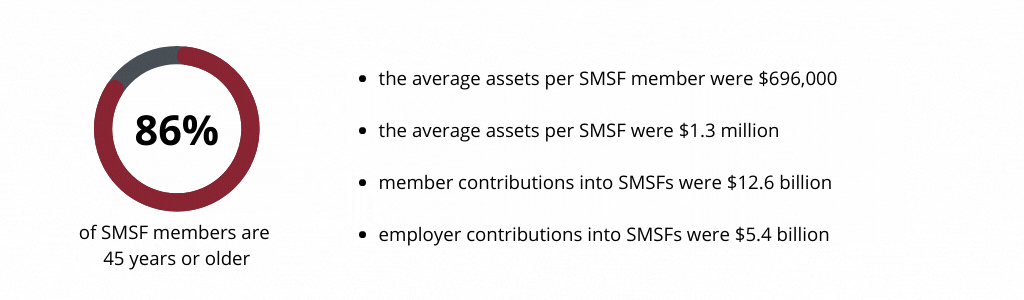
reveals there are almost 600,000 SMSFs with over 1.1 million members holding assets of $822 billion. The top two asset types are direct
holdings of listed shares (28% of total SMSF assets) and cash and term deposits (18%). In addition:
Source: Morningstar
Falling behind on your BAS lodgements looks like an administrative problem. Left long enough, it becomes an expensive one, because the GST you collected stays payable indefinitely while the GST credits you are owed disappear after four years. Here is what that looks like in dollars.
With negative gearing now quarantined for established dwellings, new house and land has become the sensible play for investors — but there is a trap in the first eighteen months. Interest on the land is denied, while interest on the construction is not. If the bank has written one loan, someone has to do the sums. Here is why it pays to split the loan before you sign.
When the draft legislation for the trust minimum tax was released, it came with a reassurance: if you do not want to restructure, you can simply make an election instead — no restructure, and no state stamp duty. That is accurate, but it is also a very small part of the decision. Here is why you should choose your structure for the eventual sale of your business, not for the announcement.